
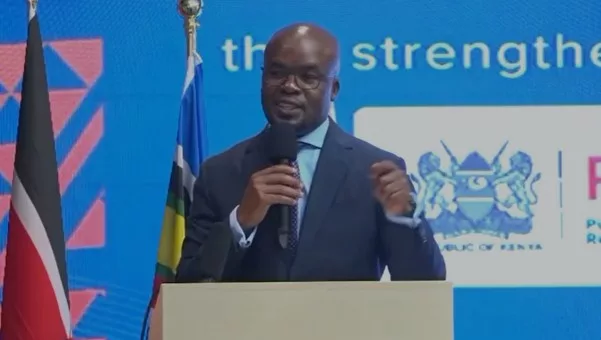
Kenya is two steps away from finishing the reform plan it needs to leave the Financial Action Task Force (FATF) grey list. Internal Security PS Raymond Omollo said in Nairobi on Tuesday that the country had substantially addressed 19 of the 21 action items by October 2026.
That covers more than 90 per cent of the requirements in Kenya’s International Cooperation Review Group (ICRG) Action Plan, which targets weaknesses in how the country fights money laundering, terrorist financing and the financing of weapons of mass destruction. Omollo spoke at the Global CFT Expert Hub Conference 2026, a three-day meeting that has drawn more than 150 delegates from governments, banks, civil society and multilateral bodies.
“This progress demonstrates our commitment to addressing identified vulnerabilities, strengthening institutional capacity and aligning our systems with international standards,” Omollo said.
The reforms reach far. They include tighter risk-based supervision of banks and of designated non-financial businesses and professions, better filing of suspicious transaction reports, a regulator for trusts and stronger collection of beneficial ownership information. Kenya has also brought its targeted financial sanctions framework in line with FATF Recommendation 6 and revised the rules for non-profit organisations.
The exit is not automatic. Under FATF rules, once a country completes all or nearly all of its plan, the body sends a team on an on-site visit to confirm the reforms work and can be sustained. If that visit goes well, the next FATF plenary considers removing the country from public monitoring.
Omollo also used the conference to defend how the government regulates charities. He cited a risk assessment of 260 faith-based organisations doing charitable work in nine higher-risk counties, which rated 76.2 per cent as medium-low risk and only 1.2 per cent as high risk. Groups rated high or medium-high risk, five per cent of the total, will face on-site reviews and mandatory annual counter-terrorist financing returns. The other 95 per cent will get routine desktop reviews.
“These findings reinforce why regulation must be informed by evidence, not assumptions,” he said. He also warned banks against cutting off whole categories of legitimate organisations over perceived risk, a practice known as de-risking. “Risk management should not become risk avoidance,” he said.
The government has made the Public Benefit Organizations Regulatory Authority (PBORA) the sector supervisor. PBORA Director General Laxmana Kiptoo said vulnerabilities should be addressed “without subjecting the entire sector to blanket restrictions”. Kenya was placed on the grey list in February 2024.